China is the world's largest trading nation, and every year millions of small businesses, freelancers, importers and members of the diaspora need to send money to China. Paying a supplier in Shenzhen, settling an invoice with a manufacturer in Yiwu, or supporting a family member running a small company in Chengdu: the motivations are diverse, but the questions are always the same. How much will the transfer really cost? How long will it take for the recipient to receive the money? And, specific to China, will the payment run into the strict annual foreign currency limits enforced by the country's regulators?
Unlike most destinations, China operates a tightly controlled foreign exchange system. Funds arriving from abroad are monitored, conversions into Chinese yuan (RMB) are capped for individuals, and businesses must justify each cross-border payment with documentation. Understanding these rules is not optional: a poorly structured transfer can be delayed, frozen or rejected. This guide explains how the system works, what the real transfer fees look like, how the main receiving channels compare, and how to choose a transparent and compliant solution.
In most countries, receiving money from abroad is a simple process: the funds arrive, the bank converts them, and the recipient can use them. China works differently. The Chinese yuan is not a fully convertible currency, meaning that its exchange into and out of foreign currencies is regulated by the state. The objective is macroeconomic: to limit speculative capital flows, stabilise the exchange rate and protect the country's financial system from sudden shocks.
For senders, this has three practical consequences. First, every incoming payment must have a clear and legitimate purpose, such as trade, services, salary or family support. Second, the way the money is received matters as much as the way it is sent: a payment to an individual's personal account is treated very differently from a payment to a company's dedicated foreign exchange account. Third, the recipient, not only the sender, carries part of the compliance burden, as Chinese banks check the origin and purpose of funds before releasing or converting them.
For businesses, this complexity is often underestimated. A small European company paying a Chinese supplier for the first time may be surprised to learn that the supplier insists on receiving funds in a specific account, or requests copies of contracts and invoices. These requests are not bureaucratic obstacles: they are the supplier's way of staying within the law. A dedicated resource explains how to pay Chinese suppliers with a simplified B2B money transfer process, from invoice verification to payment confirmation.
The central authority behind China's foreign exchange rules is the State Administration of Foreign Exchange (SAFE). Operating under the People's Bank of China, SAFE sets the rules governing how foreign currency enters, leaves and is converted within the country. Commercial banks act as the front line: they apply SAFE's rules at the counter and in their online systems.
Each individual resident in China benefits from an annual facilitation quota equivalent to USD 50,000 for converting foreign currency into RMB (known as "foreign exchange settlement"), and a separate quota of the same amount for buying foreign currency. The quota runs per calendar year, from 1 January to 31 December. Within this limit, a resident can convert foreign currency at a bank simply by presenting valid identification and declaring the purpose of the funds. Beyond it, conversions remain possible but require supporting documents proving the genuine nature of the transaction.
Crucially, the quota is strictly personal. Splitting a large payment across the accounts of relatives, friends or employees in order to stay under each person's limit is explicitly prohibited. This practice, sometimes called "quota borrowing" or "smurfing", is treated as a serious violation and can lead to account restrictions, regulatory blacklisting, fines and, in severe cases, criminal liability.
Businesses are not subject to the individual quota. Instead, a Chinese company receiving payment for exported goods or services does so through its foreign exchange settlement account, and each transaction must be supported by trade documents such as contracts, invoices or customs declarations. There is no fixed annual ceiling, but every payment must be justified. This is why paying a supplier's company account, rather than a personal account, is almost always the safer option for commercial transfers. Payments sent to an individual for what is in reality a business transaction risk consuming that person's quota, triggering compliance reviews, or being returned.
SAFE and Chinese banks have progressively tightened identity and anti-money laundering controls. Since 1 January 2026, enhanced verification of remitter information applies to many cross-border transactions above modest thresholds. For legitimate senders and recipients, these checks are a minor formality; for informal and opaque channels, they represent a growing risk of blocked funds.
Choosing the right receiving channel has a direct impact on speed, cost and compliance. China's financial landscape is dominated by a handful of state-owned banks and two mobile payment giants.
Industrial and Commercial Bank of China (ICBC) is the world's largest bank by assets and holds a vast network of corporate and personal clients. Bank of China has historically specialised in foreign exchange and international trade, making it a natural choice for exporters. China Construction Bank (CCB) completes the trio of institutions most frequently used for incoming international payments. All three accept transfers through the SWIFT network, the international messaging system that connects banks worldwide, and all apply SAFE's rules rigorously. For businesses, they remain the reference channel, since trade documentation can be submitted directly with the incoming payment.
Operated by Ant Group, Alipay is used by hundreds of millions of people in China for daily payments, from groceries to taxis. In recent years, the service has opened up considerably to foreigners and expatriates, notably by allowing international bank cards to be linked to the app for payments in China. On the receiving side, Alipay users with real-name verified accounts can receive cross-border remittances through licensed partner providers, with funds credited in RMB. These conversions count toward the recipient's annual quota. A detailed guide covers how to send money to China directly to an Alipay account, including eligibility and verification requirements.
Integrated into the WeChat messaging app, WeChat Pay (Weixin Pay) is Alipay's main competitor. Its strength lies in its ubiquity: almost every adult in China uses WeChat. Like Alipay, it supports inbound cross-border remittances through approved partners for verified users, with the same quota and identity rules applying. Mobile wallets are particularly convenient for family support and small personal amounts; for invoices, contracts and larger B2B payments, a corporate bank account remains more appropriate.
When businesses compare options, they often focus on the visible fee displayed by their bank. Yet the real cost of a SWIFT transfer to China is usually made up of several layers.
The result is that a supplier invoiced at a specific amount may receive less than expected, forcing the buyer to send a top-up payment and delaying the shipment. Timelines are also unpredictable: SWIFT transfers to China typically take two to five business days, and compliance checks can add further delays if documentation is missing. These inefficiencies are not a sign of weak regulation; Chinese and Western banks are among the most heavily supervised institutions in the world. The issue is a lack of pricing transparency. For a broader view of how regulators protect user funds, and where their oversight ends, a full guide details the role of financial regulators in protecting user funds.
CashSwap Club is built on a different principle: Peer-to-Peer (P2P) matching. Instead of sending one payment across borders through a chain of banks, the platform pairs users who have complementary currency needs. Money never physically crosses borders. The platform manages multi-currency wallets in EUR, USD, GBP and CAD that belong to users, and exchanges on the platform take place exclusively between wallets of the same currency. Local currency flows, on the other hand, travel outside the platform through domestic bank transfers or local payment solutions.
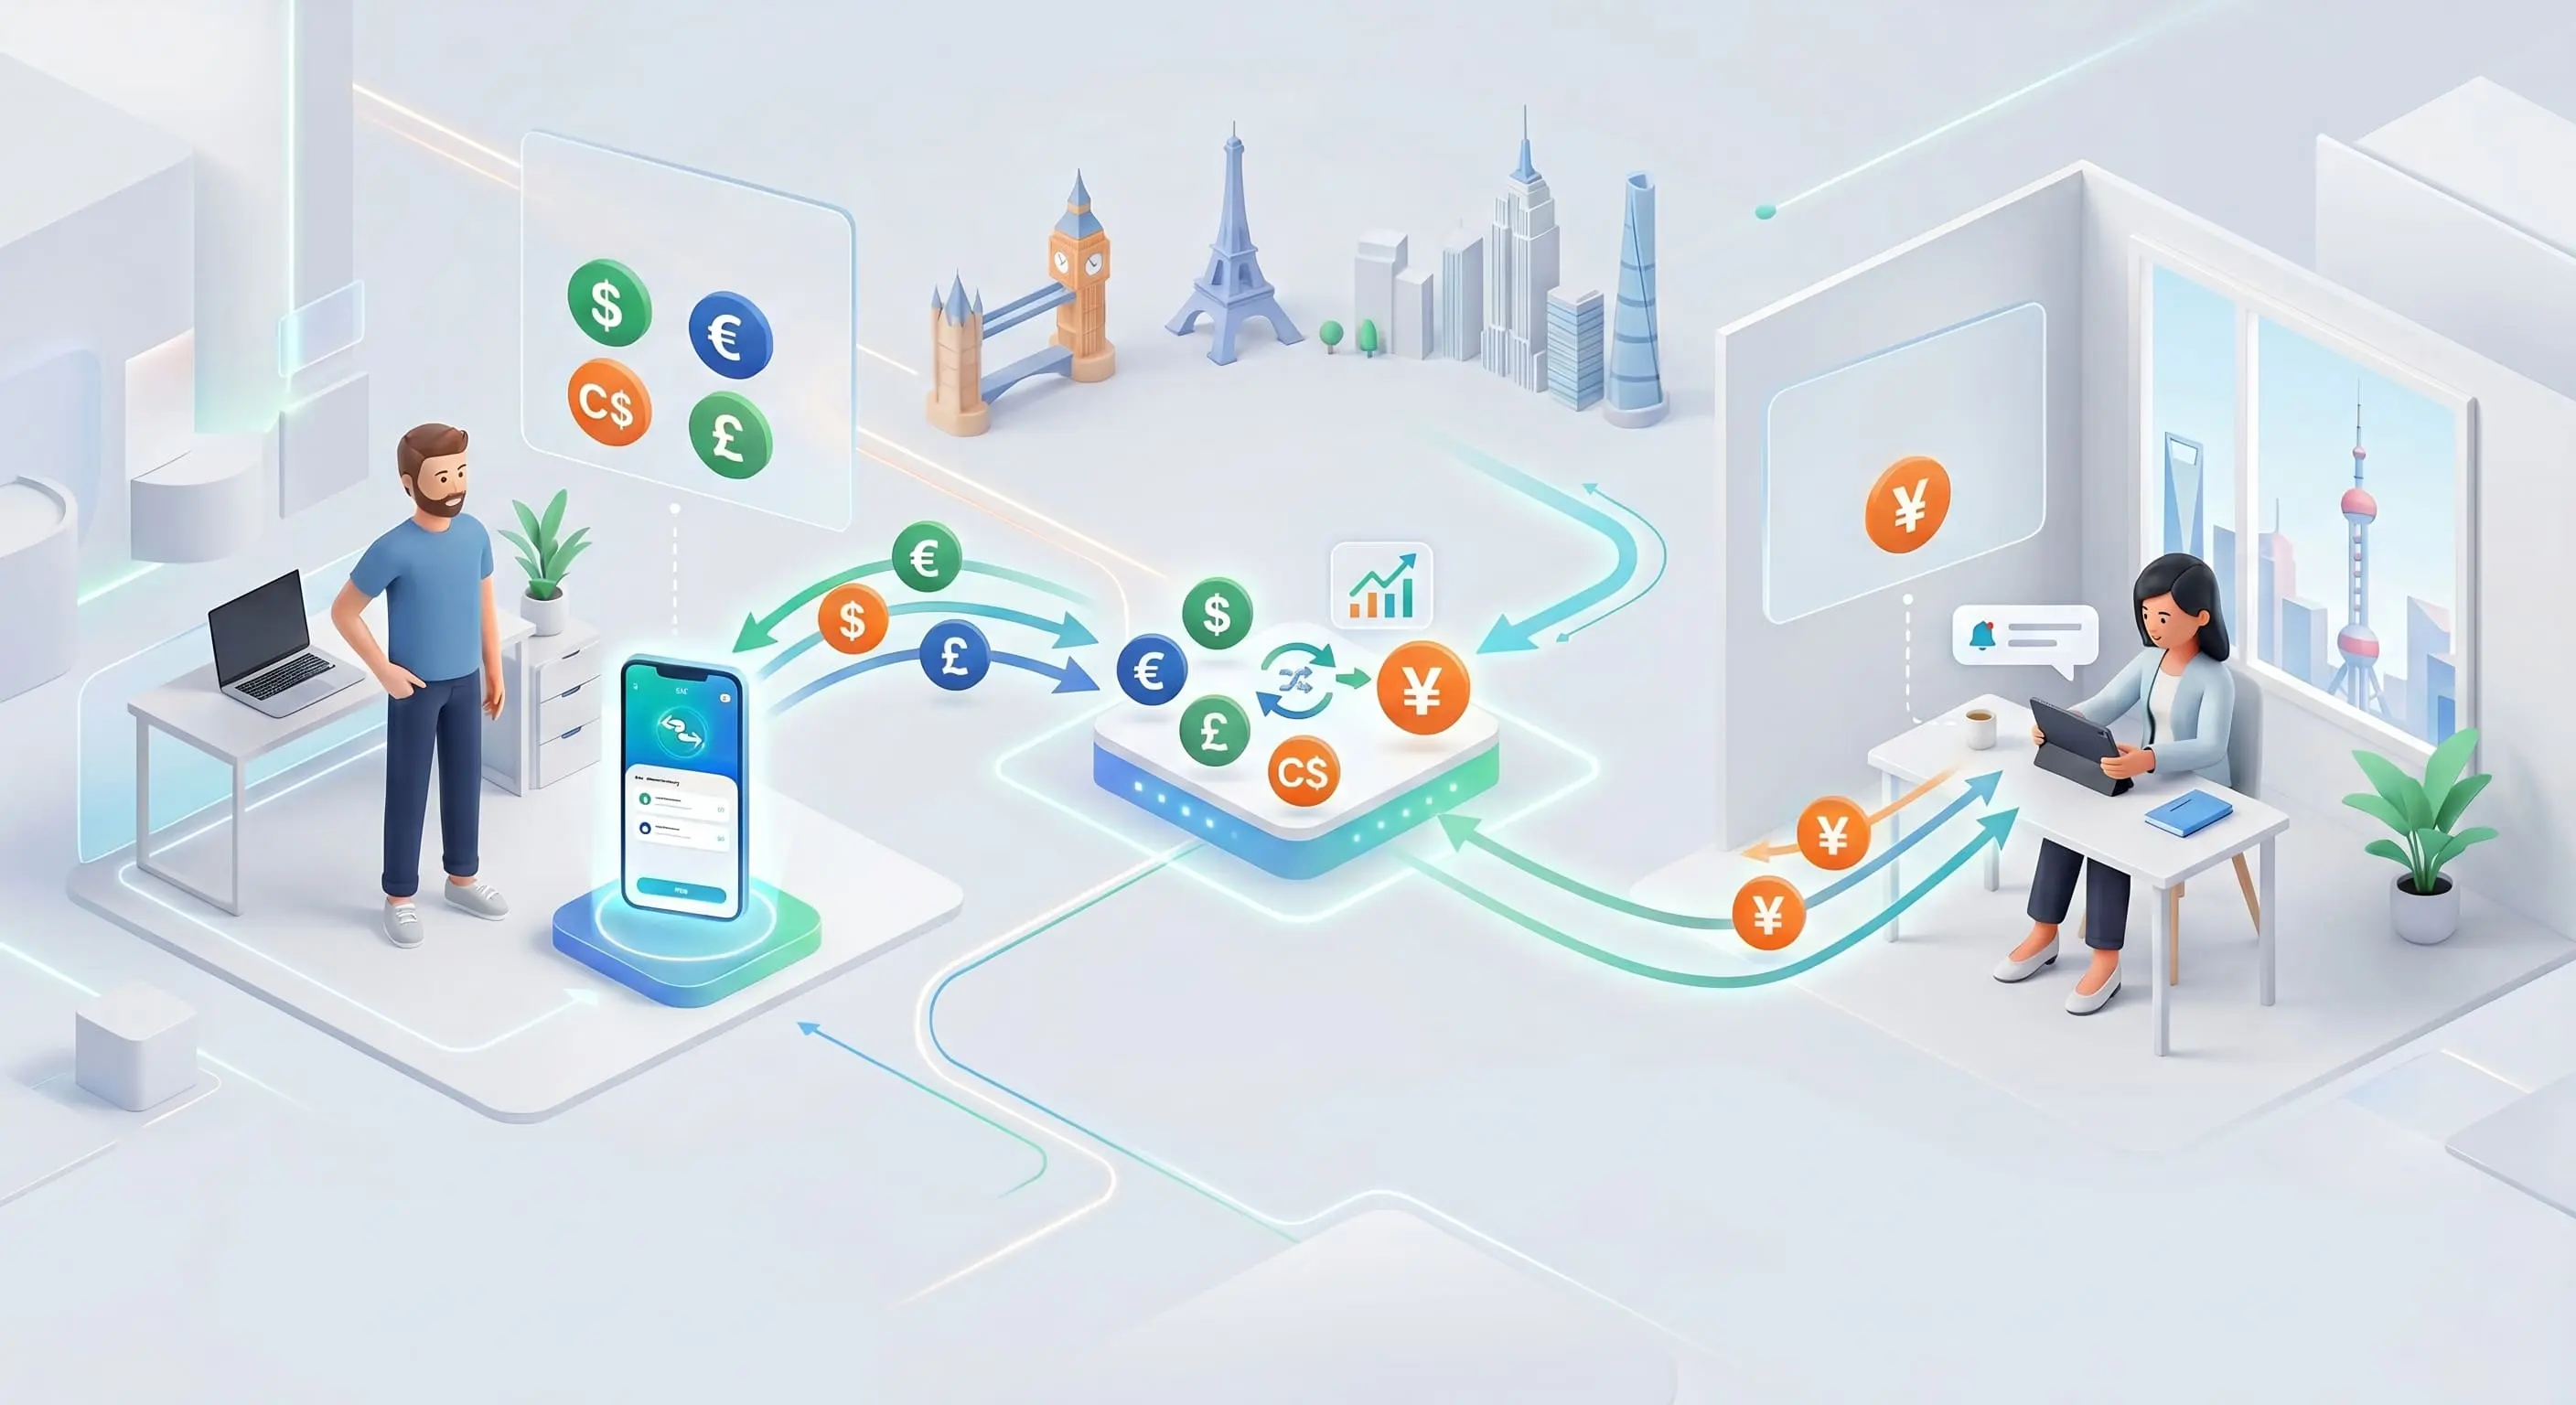
Because supply and demand are matched directly, the model removes the correspondent bank chain and its stacked fees. Users benefit from the real market rate (the interbancaire, or interbank, rate) and from minimal fixed fees displayed before any commitment. Each exchange is then mandatorily rated by both parties, creating a transparent track record for every member of the community.
For China specifically, one point deserves absolute clarity: no transfer method, P2P or otherwise, creates an exemption from SAFE rules. Chinese authorities treat informal "mirror" currency swaps outside licensed channels, often referred to as underground banking, as illegal foreign exchange trading. Any service that promises to "bypass" the annual quota or to split payments across multiple recipients should be avoided entirely, as both senders and recipients can face frozen accounts and legal consequences.
The value of a compliant P2P network lies elsewhere: in transparent pricing, in the real exchange rate on the sending side, in identity-verified counterparties, and in a clear audit trail for every transaction. Any leg of a payment that involves RMB in mainland China must run through regulated local channels, with the recipient's quota and documentation requirements fully respected. For B2B payments, the correct structure remains a payment to the supplier's company account, supported by an invoice or contract.
The user journey is designed to be simple, even for small businesses with no in-house finance team.
Registration starts with a KYC check (Know Your Customer), a standard identity verification required by anti-money laundering rules. For business use, additional information about the company and its activity may be requested.
Before committing, the live simulator shows the rate applied, the fixed fee and the exact amount involved. There are no deductions after validation, which allows invoices to be paid to the cent.
Before sending to China, the recipient's details should be confirmed: a company account at a bank such as ICBC, Bank of China or CCB for commercial payments, or a verified Alipay or WeChat Pay account for eligible personal amounts. Keeping invoices and contracts ready avoids compliance delays on the receiving side.
The user funds the operation through a domestic transfer in their own currency. The platform matches the request with a complementary counterparty, and the funds move locally on each side.
Once the funds have arrived, both parties rate the transaction. This mutual rating system builds trust and helps the community identify reliable members.
Businesses that pay the same suppliers every month can save considerable time by planning ahead: a complete guide explains how to automate recurring money transfers while keeping full control over amounts and timing. And because a P2P marketplace grows stronger with every new member, the money transfer referral programme that rewards members with P2P bonuses makes it easy to invite business partners and colleagues while earning rewards.
When searching for the best money transfer app for China, price is only one criterion. Security and compliance are just as important, because a cheap transfer that gets blocked by a Chinese bank is ultimately the most expensive option of all.
Systematic identity verification ensures that every counterparty is a real, identified person or business. Transaction monitoring, aligned with international anti-money laundering standards set by the FATF (Financial Action Task Force), helps detect unusual patterns such as payment splitting. The mandatory mutual rating system adds a layer of community oversight, as every member builds a visible reputation over time.
Before using any provider, a few checks are recommended: verify the provider's regulatory status in the official registers of its home country, confirm that the recipient in China is using a properly verified account, and keep a clear documentary trail for every commercial payment. These habits protect both sides of the transaction. The values of transparency, solidarity and fairness that guide the platform are set out in the CashSwap Club manifesto, which explains the community's vision for fairer money transfers.
Sending business payments to China requires more care than almost any other corridor. SAFE's annual limits, documentation requirements and identity checks are designed to protect the stability of the Chinese financial system, and they apply to every channel without exception. The smartest strategy is therefore not to look for shortcuts, but to combine three things: the right receiving channel (a company account for trade, a verified wallet for eligible personal amounts), complete documentation, and a transfer solution that shows the real cost upfront.
Traditional banks offer solidity but often hide their margins in the exchange rate and in intermediary fees. P2P matching offers a transparent alternative based on the real market rate and fixed fees, within a framework that places compliance first. To find out exactly how much the next payment will cost and how much will be received, the most direct step is to try the live exchange rate simulator on CashSwap Club and compare the result with a bank quote. The difference speaks for itself.
Individuals in China benefit from an annual facilitation quota equivalent to USD 50,000 for converting foreign currency into RMB, renewed every calendar year. Beyond this amount, conversion is still possible but requires supporting documents. Companies are not subject to this quota but must justify each payment with trade documents.
No. Using other people's quotas to split a single payment is explicitly prohibited by Chinese foreign exchange rules and can lead to frozen accounts, fines or more serious consequences. Commercial payments should be sent to the supplier's company account with proper documentation.
A traditional SWIFT transfer usually takes two to five business days, sometimes more if compliance checks are triggered. Delays are shortest when the recipient's account is properly verified and the payment purpose is clearly documented.
Yes, through licensed partner providers, provided the recipient has a real-name verified account. Funds are credited in RMB and count toward the recipient's annual quota. These wallets are best suited to personal amounts, while bank accounts remain preferable for business payments.

Our peer-to-peer currency exchange and money transfer platform is currently under development. We are preparing a solution that will allow you to exchange currencies with a seamless and secure experience.
To be among the first to know and not miss anything about the launch, join the club by subscribing to our newsletter.
Visuals disclosure : In the interest of transparency, please note that the images illustrating this article were created using artificial intelligence (AI) generation tools.
© CashSwap Club 2026 - All rights reserved
Designed with ❤️ in Paris • Made in France 🇫🇷
 French